As a niche market, regional aviation has grown to be a lifeblood of global air connectivity, connecting smaller cities with economic hubs through specific policy resources, fleet development, and increasing domestic demand. The model first sprang up in the mid-20th century in the United States and Europe as a feeder to legacy carriers, but it has grown substantially in markets such as India over the last decade following the introduction of the UDAN (Ude Desh ka Aam Naagrik) scheme in 2016.
Post the Wings India 2026 Summit, regional aviation is expanding into secondary and tertiary cities, with smaller aircraft and leaner crew structures aimed at delivering cost-effective connectivity. Growth has accelerated further in the post-pandemic phase, with domestic routes recovering faster than long-haul travel, according to Reuters and the International Air Transport Association (IATA).
Regional routes expand air connectivity across Tier-2 and Tier-3 cities
Origins and the Indian Push
Regional aviation originated globally as an extension of the hub-and-spoke model, where smaller carriers connected short-haul routes to major international airports. This approach improved load factors on long-haul networks, as highlighted in Boeing’s Commercial Market Outlook.
Over time, however, point-to-point connectivity gained traction, particularly in geographically fragmented and underserved regions.
In India, the segment remained underdeveloped until the mid-2010s due to high operating costs and limited infrastructure. The inflection point came with the government-backed UDAN scheme, which introduced viability gap funding, reduced airport charges, and tax incentives to stimulate regional routes.
According to Reuters, the initiative has enabled the launch of more than 450 routes and revived dozens of underutilized airports, fundamentally altering the economics of short-haul connectivity.
Fleet, Crew, and Market Dynamics
The expansion of regional aviation is closely tied to aircraft selection and operational efficiency.
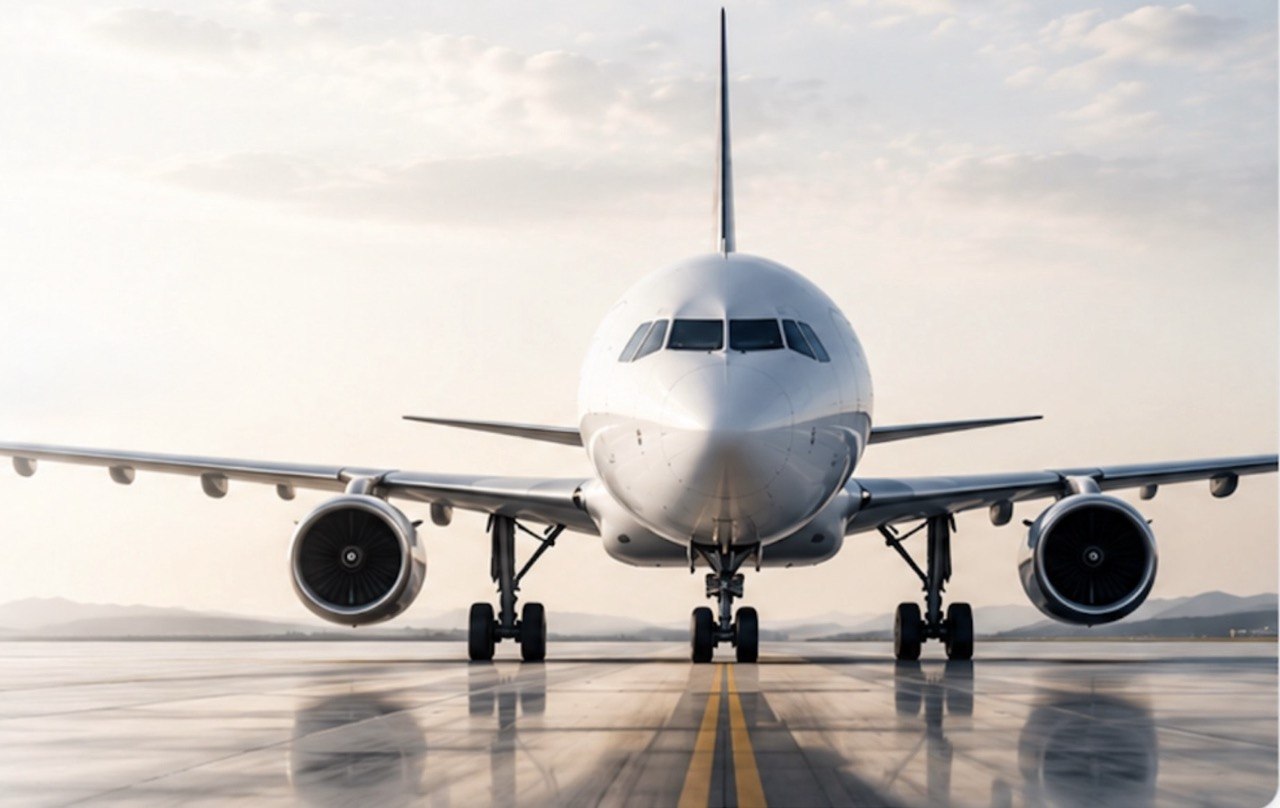
Airlines predominantly deploy turboprops such as ATR 72 aircraft and smaller narrow-body jets, typically accommodating 70 to 150 passengers. Airbus notes that such aircraft are optimized for short-haul routes due to lower fuel consumption and operating costs, enabling higher frequency services instead of large-capacity deployments.
Operational models are also structured for efficiency, with shorter turnaround times and higher aircraft utilization rates. However, the pace of expansion has intensified demand for trained personnel.
"The growth in regional operations is outpacing workforce readiness in several markets."
— Industry observation based on IATA workforce trends
The increasing requirement for pilots and cabin crew is placing measurable pressure on staffing pipelines across the sector.
At the same time, regional aviation is capturing a growing share of airline revenues. Boeing forecasts indicate that a significant portion of upcoming aircraft deliveries will be aligned with this segment, while Reuters reports that domestic and regional routes are becoming central to airline profitability in emerging markets.
Industry Perspective
Willie Walsh, Director General of IATA, underscored the structural importance of regional aviation in shaping future connectivity patterns:
"Regional aviation is opening up new demand as cities previously off the aviation map are linked. However, it requires long-term support in policies, cost-effectiveness, and prepared infrastructure."
Echoing projections from Airbus and Boeing, Walsh emphasized a gradual shift away from reliance on major metro hubs toward a more distributed network of direct city-pair connections.
He further pointed to the need for sustained investment in:
Regional airport infrastructure
Digital air traffic management systems
Workforce training and development
Without these supporting elements, the sector risks encountering capacity constraints even as demand continues to expand.
A Structural Shift in Aviation Economics
What began as a supplementary feeder network has evolved into a demand-driven ecosystem that is redefining airline route planning and market access.
The convergence of policy support, fleet optimization, and shifting passenger demand has enabled airlines to penetrate previously underserved Tier-2 and Tier-3 markets. Lower fares, improved connectivity, and decentralized route structures are driving sustained expansion.
At the same time, regional aviation is redistributing traffic away from congested metro hubs while creating new corridors of economic activity. This transition reflects a broader structural shift, where regional connectivity is no longer auxiliary but increasingly central to the aviation industry’s growth trajectory.



Join the conversation
No comments yet
Be the first to share your thoughts!
Sign In to Comment